 Coach
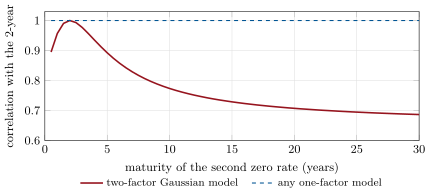
The two-factor Gaussian model (G2++) sets with , , , and fitted to the curve. The correlation of changes of the zero rates of maturities and is
with , , .
Ejemplos
Example 7.14 (Decorrelating the curve)
With a slow factor (, basis points), a fast one (, basis points) and , the model’s correlation between the two- and ten-year zero rates is 0.774, close to the Treasury estimate, and between the two- and thirty-year 0.687 (Figure 7.5). The strongly negative is typical: the fast factor moves the front against the slow factor to produce slope moves.