Tous les livres

Professionnel

Applis À propos Coach Connexion Commencer la lecture

Quantitative Finance · Glossaire

Qu'est-ce que « Two-factor Gaussian model » ?

Definition 7.13 Rates, Credit, XVA and Risk · Chapitre 7 — Short-Rate Models

The two-factor Gaussian model (G2++) sets rt=φ(t)+xt+ytr_t = \varphi(t)+x_t+y_t with dx=−κ1x dt+σ1dW1dx = -\kappa_1x\,dt+\sigma_1dW^1, dy=−κ2y dt+σ2dW2dy = -\kappa_2y\,dt+\sigma_2dW^2, d⟨W1,W2⟩=ρ dtd\langle W^1,W^2\rangle = \rho\,dt, and φ\varphi fitted to the curve. The correlation of changes of the zero rates of maturities τ1\tau_1 and τ2\tau_2 is

∑a,bba(τ1)bb(τ2)cab∑a,bba(τ1)bb(τ1)cab ∑a,bba(τ2)bb(τ2)cab,ba(τ)=B(κa,τ)τ,\frac{\sum_{a,b}b_a(\tau_1)b_b(\tau_2)c_{ab}}{\sqrt{\sum_{a,b}b_a(\tau_1)b_b(\tau_1)c_{ab}\,\sum_{a,b}b_a(\tau_2)b_b(\tau_2)c_{ab}}}, \quad b_a(\tau)=\frac{B(\kappa_a,\tau)}{\tau},

with c11=σ12c_{11}=\sigma_1^2, c22=σ22c_{22}=\sigma_2^2, c12=c21=ρσ1σ2c_{12}=c_{21}=\rho\sigma_1\sigma_2.

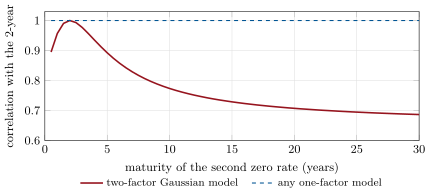
Correlation of instantaneous changes of the two-year zero rate with zero rates of other maturities: one in any one-factor model, decaying with maturity in the two-factor model of . Data: the chapter’s tutorial.
Figure 7.5. Correlation of instantaneous changes of the two-year zero rate with zero rates of other maturities: one in any one-factor model, decaying with maturity in the two-factor model of Example 7.14. Data: the chapter’s tutorial.

Exemples

Example 7.14 (Decorrelating the curve)

With a slow factor (κ1=2%\kappa_1=2\%, σ1=75\sigma_1=75 basis points), a fast one (κ2=50%\kappa_2=50\%, σ2=90\sigma_2=90 basis points) and ρ=−0.8\rho=-0.8, the model’s correlation between the two- and ten-year zero rates is 0.774, close to the Treasury estimate, and between the two- and thirty-year 0.687 (Figure 7.5). The strongly negative ρ\rho is typical: the fast factor moves the front against the slow factor to produce slope moves.

Lire dans le chapitre →