
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Variation margin and initial margin؟

يُعرف أيضًا باسم: variation margin · initial margin

Definition 5.7 Markets I: The Ecosystem and Exchange-Traded Markets · الفصل 5 — Clearing and Settlement

Variation margin is the daily (or intraday) payment of the change in value of a member’s open positions: losers pay, the CCP passes the cash to winners, and exposures restart from zero. Initial margin is collateral deposited against the loss the CCP could suffer on the member’s positions between its last variation-margin payment and the moment the CCP has finished closing them out, a delay called the margin period of risk.
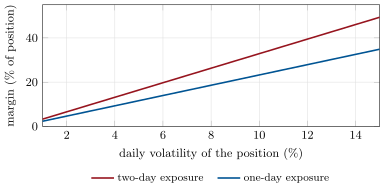
The value-at-risk margin of  at 99% confidence. Margin is linear in volatility: a stock that becomes five times more volatile overnight costs five times more to clear the next morning. Data: computed by the chapter’s script.
Figure 5.3. The value-at-risk margin of Method 5.8 at 99% confidence. Margin is linear in volatility: a stock that becomes five times more volatile overnight costs five times more to clear the next morning. Data: computed by the chapter’s script.

أمثلة

Example 5.12 (September 2008)

When Lehman Brothers defaulted on Monday 15 September 2008, the London clearing house for interest-rate swaps held its portfolio: 66 390 trades with a notional value of $9 trillion in five currencies, against about $2 billion of initial margin. Traders seconded from member banks hedged the portfolio alongside the clearing house’s risk team; between 24 September and 3 October the hedged currency portfolios were auctioned. The clearing house reported that the default was managed well within the margin held and that its default fund was not used. The episode became the standard argument for the clearing mandates that followed.

اقرأ في الفصل →