 Coach
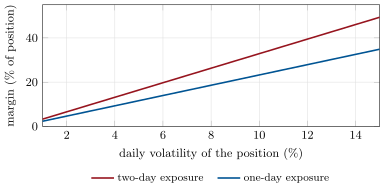
Variation margin is the daily (or intraday) payment of the change in value of a member’s open positions: losers pay, the CCP passes the cash to winners, and exposures restart from zero. Initial margin is collateral deposited against the loss the CCP could suffer on the member’s positions between its last variation-margin payment and the moment the CCP has finished closing them out, a delay called the margin period of risk.
Exemples
Example 5.12 (September 2008)
When Lehman Brothers defaulted on Monday 15 September 2008, the London clearing house for interest-rate swaps held its portfolio: 66 390 trades with a notional value of $9 trillion in five currencies, against about $2 billion of initial margin. Traders seconded from member banks hedged the portfolio alongside the clearing house’s risk team; between 24 September and 3 October the hedged currency portfolios were auctioned. The clearing house reported that the default was managed well within the margin held and that its default fund was not used. The episode became the standard argument for the clearing mandates that followed.