 المدرب
The VIX term-structure slope is the difference, or ratio, between a later and an earlier VIX future (often the second and the first contract) or between the first contract and the index; a positive slope (contango) means that longs pay a roll-down as each contract converges to the index.
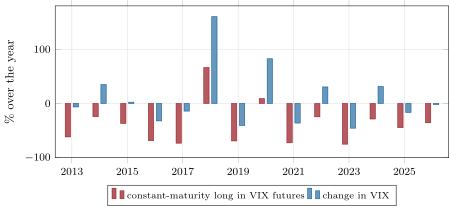
s2_fetch_vx.