
Todos os livros

Profissional

Apps Sobre Coach Entrar Começar a ler

Quantitative Finance · Glossário

O que é VIX term-structure slope?

Definition 5.1 Strategies II: Volatility, Relative Value, Macro and the Bank Desks · Capítulo 5 — The Volatility-Index Complex

The VIX term-structure slope is the difference, or ratio, between a later and an earlier VIX future (often the second and the first contract) or between the first contract and the index; a positive slope (contango) means that longs pay a roll-down as each contract converges to the index.
Each calendar year from 2013 to 2026 (2026 to 24 September): the return of a long position in VIX futures held at a constant maturity of one contract cycle, rebuilt from Cboe’s daily settlements, and the change in VIX. The long position lost in every year but 2018 and 2020. Derived from Cboe’s futures and index histories; the raw data are not redistributed. Data: s2_fetch_vx.
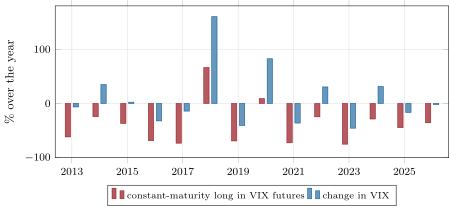
Figure 5.1. Each calendar year from 2013 to 2026 (2026 to 24 September): the return of a long position in VIX futures held at a constant maturity of one contract cycle, rebuilt from Cboe’s daily settlements, and the change in VIX. The long position lost in every year but 2018 and 2020. Derived from Cboe’s futures and index histories; the raw data are not redistributed. Data: s2_fetch_vx.
Ler no capítulo →