
Tous les livres

Professionnel

Applis À propos Coach Connexion Commencer la lecture

Quantitative Finance · Glossaire

Qu'est-ce que « Volatility per trade » ?

Definition 3.2 Microstructure and Execution · Chapitre 3 — Empirical Facts of Order Books

The volatility per trade σ1\sigma_1 of an instrument is the standard deviation of the change in the mid price between one trade and the next.
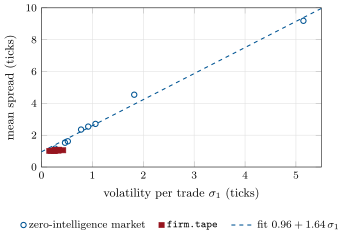
Mean spread against volatility per trade: eight configurations of chapter 1’s zero-intelligence market (100 000 events each) and ten of firm.tape (20 simulated minutes each, informed intensity and efficient-price jump rate varied). The zero-intelligence spreads follow the line; firm.tape’s stay near one tick. Data: mx_facts.spread_vs_vol_zi, mx_facts.spread_vs_vol.
Figure 3.1. Mean spread against volatility per trade: eight configurations of chapter 1’s zero-intelligence market (100 000 events each) and ten of firm.tape (20 simulated minutes each, informed intensity and efficient-price jump rate varied). The zero-intelligence spreads follow the line; firm.tape’s stay near one tick. Data: mx_facts.spread_vs_vol_zi, mx_facts.spread_vs_vol.
Lire dans le chapitre →