Coach
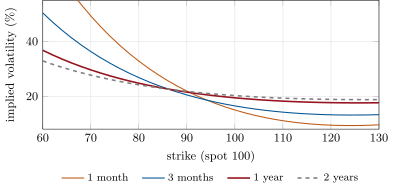
The volatility surface of an underlying is the function that gives, for every strike and expiry, the implied volatility of the European option, computed with Black’s formula on the forward of that expiry. Its natural coordinates are the log-moneyness , which measures a strike against the forward of its own expiry, and the total implied variance , the variance of the log-return to expiry that the price implies.