
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Wrong-way risk؟

Definition 17.11 Rates, Credit, XVA and Risk · الفصل 17 — Counterparty Exposure

Wrong-way risk is a positive dependence between a counterparty’s probability of default and the bank’s exposure to it: the exposure is largest when default is likeliest. It is specific when the dependence is built into the trade (protection bought from a counterparty on itself or on its own country) and general when it comes through common market factors.
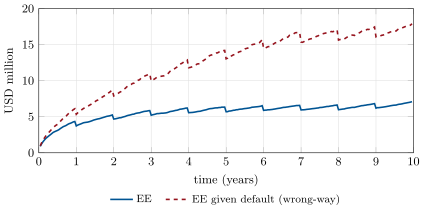
Expected exposure of the cross-currency swap, unconditionally and conditional on the counterparty defaulting at each date, when the counterparty’s hazard rises as the euro falls. The exposures that matter are those in the scenarios where the counterparty defaults. Data: the chapter’s tutorial.
Figure 17.5. Expected exposure of the cross-currency swap, unconditionally and conditional on the counterparty defaulting at each date, when the counterparty’s hazard rises as the euro falls. The exposures that matter are those in the scenarios where the counterparty defaults. Data: the chapter’s tutorial.

أمثلة

Example 17.12 (A counterparty that weakens with the euro)

Let the counterparty of the cross-currency swap have a hazard rate of 2%×(Xt/FX(0,t))−52\%\times(X_t/F_X(0,t))^{-5}: a 10% fall of the euro below its forward raises its hazard by about 70%. The bank’s exposure is largest when the euro has fallen. Weighting the paths by the probability of default in each period, the expected exposure conditional on default is 2.52 times the unconditional EE at its peak, and 2.22 times on average over the life (Figure 17.5).

اقرأ في الفصل →