 المدرب
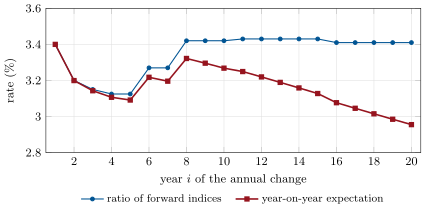
The year-on-year convexity adjustment of period is the difference between and the ratio of forward indices .
أمثلة
Example 11.5 (Sterling year-on-year convexity)
On illustrative sterling curves (SONIA zero rates of 3.6–4.2%, RPI zero-coupon swaps of 3.2–3.4%) with , basis points, and , the adjustment is zero for the first year, basis points for the fourth, for the tenth (forward 3.42%, year-on-year expectation 3.27%) and for the nineteenth (Figure 11.2). The ten-year year-on-year swap rate is 3.22% against a ten-year zero-coupon rate of 3.28%. A simulation of the model reproduces the tenth year’s expectation, 1.03268, at 1.03277 with a standard error of 0.00013.