
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Asian option؟

Definition 16.1 Derivatives and Volatility · الفصل 16 — Asians, Lookbacks, Cliquets and Forward-Starts

An Asian option pays on the average of the underlying over a set of fixing dates: the average-rate form pays (Sˉ−K)+(\bar S-K)^+ (the average-price option of One Quant Book 3, chapter 12), and the average-strike form pays (ST−Sˉ)+(S_T-\bar S)^+. The average is arithmetic unless stated.
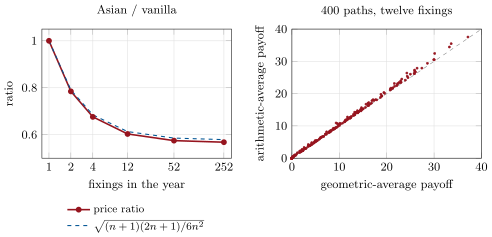
Left: the price of an at-the-money one-year Asian call relative to the vanilla, by the number of fixings, against the volatility factor of the geometric average. Right: the arithmetic and geometric payoffs path by path: nearly the same random variable, which is why the geometric Asian, known in closed form, is an efficient control variate. Data: the tutorial.
Figure 16.1. Left: the price of an at-the-money one-year Asian call relative to the vanilla, by the number of fixings, against the volatility factor of the geometric average. Right: the arithmetic and geometric payoffs path by path: nearly the same random variable, which is why the geometric Asian, known in closed form, is an efficient control variate. Data: the tutorial.

أمثلة

Example 16.2 (Where the 40% went)

Spot and strike 100, one year, r=3%r=3\%, q=1%q=1\%, volatility 20%. The vanilla call is worth 8.83, and the call on the average of twelve monthly fixings is worth 5.32, 40% less. The variance factor is 13×25/(6×144)=0.37613\times25/(6\times144)=0.376, so the geometric average moves with a volatility of 0.61×20%=12.3%0.61\times20\%=12.3\%. As the fixings multiply, the Asian’s price relative to the vanilla falls from 0.78 with two fixings to 0.68 with four, 0.60 with twelve and 0.57 with daily fixings. It tracks the volatility factor (n+1)(2n+1)/(6n2)\sqrt{(n+1)(2n+1)/(6n^2)}: 0.79, 0.68, 0.61 and 0.58 (Figure 16.1, left).

اقرأ في الفصل →