 Coach
An Asian option pays on the average of the underlying over a set of fixing dates: the average-rate form pays (the average-price option of One Quant Book 3, chapter 12), and the average-strike form pays . The average is arithmetic unless stated.
Exemples
Example 16.2 (Where the 40% went)
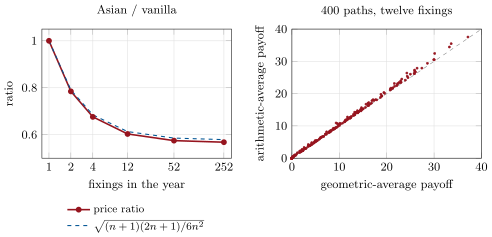
Spot and strike 100, one year, , , volatility 20%. The vanilla call is worth 8.83, and the call on the average of twelve monthly fixings is worth 5.32, 40% less. The variance factor is , so the geometric average moves with a volatility of . As the fixings multiply, the Asian’s price relative to the vanilla falls from 0.78 with two fixings to 0.68 with four, 0.60 with twelve and 0.57 with daily fixings. It tracks the volatility factor : 0.79, 0.68, 0.61 and 0.58 (Figure 16.1, left).