
सभी किताबें

पेशेवर

ऐप्स परिचय Coach लॉग इन पढ़ना शुरू करें

Quantitative Finance · शब्दावली

Autocovariance, autocorrelation and partial autocorrelation functions क्या है?

अन्य नाम: autocovariance function · autocorrelation function · partial autocorrelation function

Definition 17.2 Quantitative Methods · अध्याय 17 — Linear Time Series

For a weakly stationary process, the autocovariance function is γ(h)=Cov⁡(Xt,Xt+h)\gamma(h) = \Cov(X_t, X_{t+h}), and the autocorrelation function is ρ(h)=γ(h)/γ(0)\rho(h) = \gamma(h)/\gamma(0). The partial autocorrelation function at lag hh is the last coefficient ϕhh\phi_{hh} of the best linear predictor of Xt+hX_{t+h} from Xt+h−1,…,XtX_{t+h-1}, \dots, X_t: the correlation at lag hh once the intermediate lags are accounted for.
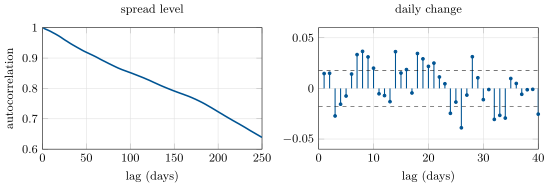
Sample autocorrelations of the 2s10s Treasury spread, 1 June 1976 to 22 September 2026 (12 574 days). Left: the level, lags 1 to 250, from 0.9987 down. Right: the daily change, lags 1 to 40, with the ± 2/√ n band. Data: FRED series DGS10 and DGS2 (Board of Governors of the Federal Reserve System, H.15).
Figure 17.1. Sample autocorrelations of the 2s10s Treasury spread, 1 June 1976 to 22 September 2026 (12 574 days). Left: the level, lags 1 to 250, from 0.9987 down. Right: the daily change, lags 1 to 40, with the ±2/n\pm 2/\sqrt n band. Data: FRED series DGS10 and DGS2 (Board of Governors of the Federal Reserve System, H.15).
अध्याय में पढ़ें →