Coach
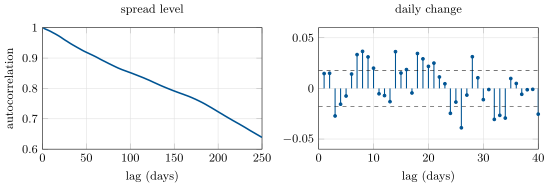
For a weakly stationary process, the autocovariance function is , and the autocorrelation function is . The partial autocorrelation function at lag is the last coefficient of the best linear predictor of from : the correlation at lag once the intermediate lags are accounted for.