सभी किताबें

पेशेवर

ऐप्स परिचय Coach लॉग इन पढ़ना शुरू करें

Quantitative Finance · शब्दावली

Bergomi model क्या है?

Definition 12.4 Derivatives and Volatility · अध्याय 12 — Rough Volatility and Forward-Variance Models

The Bergomi model is the forward-variance model with lognormal dynamics and exponentially decaying volatility along the curve. In its one-factor form,

dξt(u)=η e−κ(u−t) ξt(u) dWt1,ξt(u)=ξ0(u)exp⁡(ηe−κ(u−t)Xt−12η2e−2κ(u−t)E[Xt2]),d\xi_t(u)=\eta\,e^{-\kappa(u-t)}\,\xi_t(u)\,dW^1_t,\qquad \xi_t(u)=\xi_0(u)\exp\Bigl(\eta e^{-\kappa(u-t)}X_t-\tfrac12\eta^2e^{-2\kappa(u-t)}\E[X_t^2]\Bigr),

with Xt=∫0te−κ(t−s)dWs1X_t=\int_0^te^{-\kappa(t-s)}dW^1_s an Ornstein–Uhlenbeck factor and d⟨W1,WS⟩=ρ dtd\langle W^1,W^S\rangle=\rho\,dt for the Brownian motion WSW^S of the underlying. The two-factor form adds a second factor with a faster decay and mixes the two.

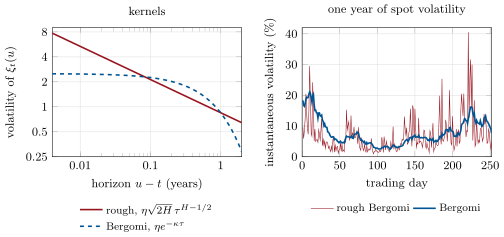
Left: the volatility of forward variance by horizon, for the rough kernel (H=0.1, =1.9) and a one-factor Bergomi kernel matched to it at one month and one year (=2.51, =1.08). Only the rough kernel explodes at short horizons. Right: one year of daily spot volatility from each model, driven by the same Brownian increments, with a flat 20% forward volatility. Data: the chapter’s code.
Figure 12.2. Left: the volatility of forward variance by horizon, for the rough kernel (H=0.1H=0.1, η=1.9\eta=1.9) and a one-factor Bergomi kernel matched to it at one month and one year (η=2.51\eta=2.51, κ=1.08\kappa=1.08). Only the rough kernel explodes at short horizons. Right: one year of daily spot volatility from each model, driven by the same Brownian increments, with a flat 20% forward volatility. Data: the chapter’s code.
अध्याय में पढ़ें →