 Pelatih
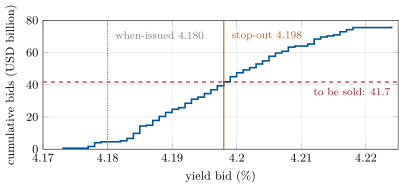
The bid-to-cover ratio is the amount bid divided by the amount offered. The auction tail is the stop-out yield minus the when-issued yield (Definition 4.6) at the bid deadline: positive, the auction cleared cheaper than the market (it tailed); negative, richer (it stopped through).
Contoh
Example 4.5 (A synthetic ten-year auction)
USD 42 billion of ten-year notes are offered; USD 300 million of noncompetitive bids leave USD 41.7 billion for 76.1 billion of competitive bids. The when-issued note trades at 4.180% at 13:00. The bids of Figure 4.1 reach 41.7 billion at 4.198%: that is the stop-out, bids there are filled at 95.02%, the tail is 1.8 basis points and the bid-to-cover ratio 1.82. Indirect bidders (investors bidding through a dealer) take 51.1%, direct bidders 10.6% and dealers 38.3%. The coupon is set at 4.125%, and every winner pays 99.409 for a note that the market valued at 4.180% a minute before. The auction is simulated; the procedure is the Treasury’s.