 Pelatih
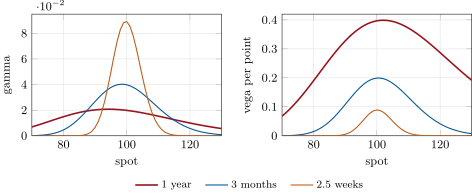
The cash gamma of a position is : the P&L of the delta-hedged position per unit of squared return, since . Risk reports also give , the change of the cash delta for a 1% move. A straddle is a call and a put with the same strike and expiry: at the money its delta is close to zero and its gamma and vega are twice the call’s.
Contoh
Example 4.6 (The desk’s month)
The one-month at-the-money straddle on a share at 100 is worth 4.6059 at 20 volatility and 5.7570 at 25, with zero rates. A desk short 1 000 straddles (multiplier 100) expects to lose , about USD 115 100, when realised volatility comes in at 25. Its vega, 0.2302 per point per straddle, times five points gives nearly the same number: for small changes the expected loss is vega times the volatility gap.