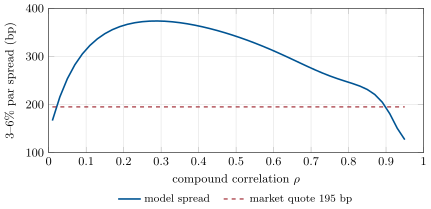
The compound correlation of a tranche is the single correlation at which the one-factor Gaussian copula reprices it, with both its attachment and detachment losses computed at that correlation.
 Coach
लॉग इन
पढ़ना शुरू करें
Quantitative Finance · शब्दावली
The compound correlation of a tranche is the single correlation at which the one-factor Gaussian copula reprices it, with both its attachment and detachment losses computed at that correlation.