Todos os livros

Profissional

Apps Sobre Coach Entrar Começar a ler

Quantitative Finance · Glossário

O que é Compound correlation?

Definition 15.5 Rates, Credit, XVA and Risk · Capítulo 15 — Portfolio Credit

The compound correlation of a tranche is the single correlation at which the one-factor Gaussian copula reprices it, with both its attachment and detachment losses computed at that correlation.
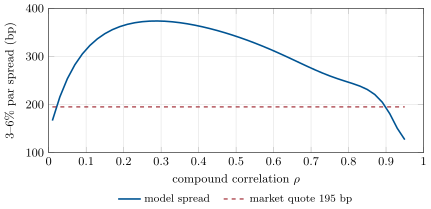

The 3–6% tranche’s model spread against the compound correlation. The curve is humped, so the quote of 195 basis points is matched at two correlations (2.1% and 89.9%), and a quote above the hump by none. Data: the chapter’s tutorial.
Figure 15.2. The 3–6% tranche’s model spread against the compound correlation. The curve is humped, so the quote of 195 basis points is matched at two correlations (2.1% and 89.9%), and a quote above the hump by none. Data: the chapter’s tutorial.
Ler no capítulo →