Tous les livres

Professionnel

Applis À propos Coach Connexion Commencer la lecture

Quantitative Finance · Glossaire

Qu'est-ce que « Conjugate gradient method, preconditioner » ?

Aussi appelé : conjugate gradient method · preconditioner

Definition 25.9 Quantitative Methods · Chapitre 25 — Floating Point and Numerical Linear Algebra

The conjugate gradient method (Hestenes and Stiefel, 1952) solves Ax=bAx = b for symmetric positive-definite AA by minimising 12x⊤Ax−b⊤x\frac12x^\top Ax - b^\top x along mutually AA-conjugate directions built from the residuals. A preconditioner M≈AM \approx A replaces the system by one with M−1AM^{-1}A, of smaller condition number.

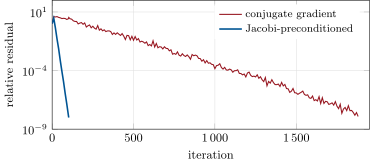
Conjugate gradient on a badly scaled symmetric positive-definite system of dimension 400 (condition number 1.1 × 10⁵), with and without a diagonal preconditioner: relative residual against the iteration (the preconditioned run stops at 102). Data: the chapter’s tutorial, seeded.
Figure 25.5. Conjugate gradient on a badly scaled symmetric positive-definite system of dimension 400 (condition number 1.1×1051.1 \times 10^5), with and without a diagonal preconditioner: relative residual against the iteration (the preconditioned run stops at 102). Data: the chapter’s tutorial, seeded.
Lire dans le chapitre →