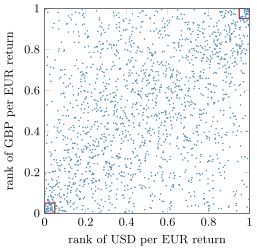
A copula is a joint distribution function on with uniform margins. The lower tail dependence coefficient of with continuous margins is , and the upper one is defined symmetrically.
 Coach
Inloggen
Begin met lezen
Quantitative Finance · Begrippenlijst
Ook bekend als: copula · tail dependence coefficient
A copula is a joint distribution function on with uniform margins. The lower tail dependence coefficient of with continuous margins is , and the upper one is defined symmetrically.