Todos os livros

Profissional

Apps Sobre Coach Entrar Começar a ler

Quantitative Finance · Glossário

O que é Copula, tail dependence coefficient?

Também chamado de: copula · tail dependence coefficient

Definition 15.6 Quantitative Methods · Capítulo 15 — Robust Statistics and Heavy Tails

A copula is a joint distribution function on [0,1]d[0, 1]^d with uniform margins. The lower tail dependence coefficient of (X,Y)(X, Y) with continuous margins FX,FYF_X, F_Y is λL=lim⁡q↓0P(FY(Y)≤q∣FX(X)≤q)\lambda_L = \lim_{q \downarrow 0}\P(F_Y(Y) \le q \mid F_X(X) \le q), and the upper one is defined symmetrically.
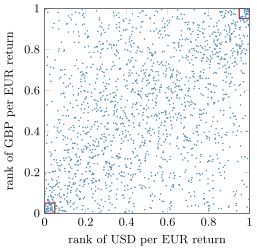
The empirical copula of daily euro returns against the dollar and the pound, 1999–2026 (every fourth day shown): each point is a day’s pair of ranks scaled to (0, 1). The squares mark the joint 5% tails, where 32% of the dollar’s worst days are also among the pound’s worst, against 20% under a Gaussian copula with the same correlation. Data: ECB euro reference rates (source: ECB statistics).
Figure 15.2. The empirical copula of daily euro returns against the dollar and the pound, 1999–2026 (every fourth day shown): each point is a day’s pair of ranks scaled to (0,1)(0, 1). The squares mark the joint 5% tails, where 32% of the dollar’s worst days are also among the pound’s worst, against 20% under a Gaussian copula with the same correlation. Data: ECB euro reference rates (source: ECB statistics).
Ler no capítulo →
