
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Effective duration, negative convexity؟

يُعرف أيضًا باسم: effective duration · negative convexity

Definition 12.7 Markets II: Rates, FX and Credit · الفصل 12 — Mortgages and Agencies

The effective duration of a security whose cash flows depend on rates is (P−−P+)/(2P Δy)(P_- - P_+)/(2P\,\Delta y), where P±P_\pm are its prices after shifting rates by ±Δy\pm\Delta y and re-running the model of its cash flows. A security has negative convexity over a range of rates when its effective duration falls as rates fall: its price rises less than it falls for equal moves.
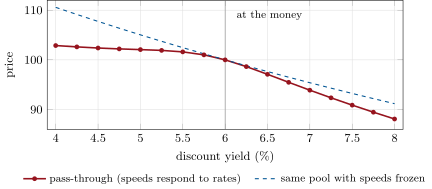
Price of the chapter’s 6% pass-through against the discount yield, when prepayment speeds follow the refinancing S-curve and when they are frozen at their at-the-money value. Below the money the pass-through’s price flattens out: negative convexity. Illustrative model; data: the chapter’s tutorial.
Figure 12.3. Price of the chapter’s 6% pass-through against the discount yield, when prepayment speeds follow the refinancing S-curve and when they are frozen at their at-the-money value. Below the money the pass-through’s price flattens out: negative convexity. Illustrative model; data: the chapter’s tutorial.
اقرأ في الفصل →