Coach
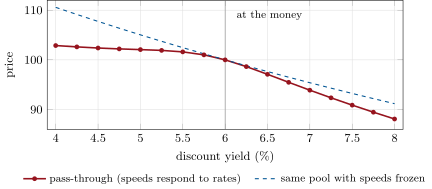
The effective duration of a security whose cash flows depend on rates is , where are its prices after shifting rates by and re-running the model of its cash flows. A security has negative convexity over a range of rates when its effective duration falls as rates fall: its price rises less than it falls for equal moves.