
Semua buku

Profesional

Aplikasi Tentang Pelatih Masuk Mulai membaca

Quantitative Finance · Glosarium

Apa itu Effective duration, negative convexity?

Dikenal juga sebagai: effective duration · negative convexity

Definition 12.7 Markets II: Rates, FX and Credit · Bab 12 — Mortgages and Agencies

The effective duration of a security whose cash flows depend on rates is (P−−P+)/(2P Δy)(P_- - P_+)/(2P\,\Delta y), where P±P_\pm are its prices after shifting rates by ±Δy\pm\Delta y and re-running the model of its cash flows. A security has negative convexity over a range of rates when its effective duration falls as rates fall: its price rises less than it falls for equal moves.
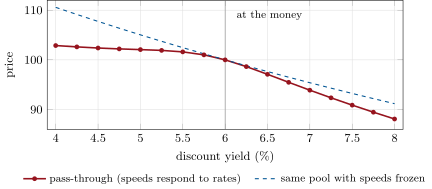
Price of the chapter’s 6% pass-through against the discount yield, when prepayment speeds follow the refinancing S-curve and when they are frozen at their at-the-money value. Below the money the pass-through’s price flattens out: negative convexity. Illustrative model; data: the chapter’s tutorial.
Figure 12.3. Price of the chapter’s 6% pass-through against the discount yield, when prepayment speeds follow the refinancing S-curve and when they are frozen at their at-the-money value. Below the money the pass-through’s price flattens out: negative convexity. Illustrative model; data: the chapter’s tutorial.
Baca dalam konteks →