Coach
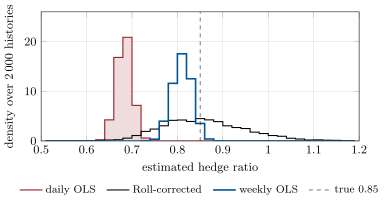
An errors-in-variables model observes the regressor with noise, , with independent of and of the equation error. The resulting shrinkage of the OLS slope toward zero is the attenuation bias. Total least squares fits the line minimising the sum of squared perpendicular distances, which is consistent when the errors in and in have equal variances.