Todos os livros

Profissional

Apps Sobre Coach Entrar Começar a ler

Quantitative Finance · Glossário

O que é Errors-in-variables, attenuation bias, total least squares?

Também chamado de: errors-in-variables · attenuation bias · total least squares

Definition 16.9 Quantitative Methods · Capítulo 16 — Linear Models under Stress

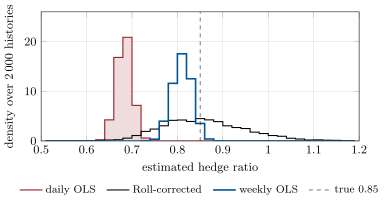
An errors-in-variables model observes the regressor with noise, x~=x+u\tilde x = x + u, with uu independent of xx and of the equation error. The resulting shrinkage of the OLS slope toward zero is the attenuation bias. Total least squares fits the line minimising the sum of squared perpendicular distances, which is consistent when the errors in xx and in yy have equal variances.

Sampling distributions of three hedge-ratio estimates over 2 000 simulated two-year histories: daily OLS on the noisy future prices (mean 0.683, attenuated by 0.80), the same divided by the attenuation estimated from the future’s first autocorrelation (mean 0.862, standard deviation 0.095), and OLS on weekly changes (mean 0.810, standard deviation 0.022). Data: the chapter’s tutorial, seeded.
Figure 16.4. Sampling distributions of three hedge-ratio estimates over 2 000 simulated two-year histories: daily OLS on the noisy future prices (mean 0.683, attenuated by 0.80), the same divided by the attenuation estimated from the future’s first autocorrelation (mean 0.862, standard deviation 0.095), and OLS on weekly changes (mean 0.810, standard deviation 0.022). Data: the chapter’s tutorial, seeded.
Ler no capítulo →