جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Event variance؟

Definition 8.7 Derivatives and Volatility · الفصل 8 — Parametrising the Surface

The event variance of a scheduled announcement (an earnings release, a central-bank decision, a trial result) is the variance of the log-return caused by the announcement itself. Between two expiries that bracket the event it is the excess of total variance over what the diffusive rate of the earlier expiry would accrue: wevent=w(T2)−(w(T1)/T1)T2w_{\mathrm{event}}=w(T_2)-\bigl(w(T_1)/T_1\bigr)T_2.

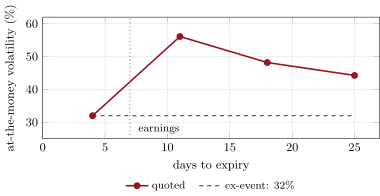
At-the-money term structure of a share around its earnings release (dotted). Expiries after the release carry one lump of variance, worth 8.0% of standard deviation; its weight falls as 1/T with the expiry. Illustrative quotes.
Figure 8.4. At-the-money term structure of a share around its earnings release (dotted). Expiries after the release carry one lump of variance, worth 8.0% of standard deviation; its weight falls as 1/T1/T with the expiry. Illustrative quotes.

أمثلة

Example 8.8 (An earnings week)

A share reports after the close on day 7. At-the-money volatilities are 32.0% for the expiry in 4 days, 56.1% in 11 days, 48.2% in 18 and 44.3% in 25. The event variance is 0.5612×11/365−0.322×11/365=0.00640.561^2\times11/365-0.32^2\times11/365=0.0064: a standard deviation of 8.0% for the move on the announcement, an expected absolute move of 8.0%×2/π=6.4%8.0\%\times\sqrt{2/\pi}=6.4\%. Removing it, the 18-day expiry’s volatility is 32.0%: the whole term structure beyond the event is one diffusive volatility plus one jump (Figure 8.4).

اقرأ في الفصل →