 Coach
The event variance of a scheduled announcement (an earnings release, a central-bank decision, a trial result) is the variance of the log-return caused by the announcement itself. Between two expiries that bracket the event it is the excess of total variance over what the diffusive rate of the earlier expiry would accrue: .
Exemplos
Example 8.8 (An earnings week)
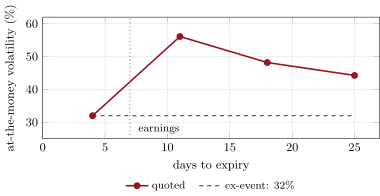
A share reports after the close on day 7. At-the-money volatilities are 32.0% for the expiry in 4 days, 56.1% in 11 days, 48.2% in 18 and 44.3% in 25. The event variance is : a standard deviation of 8.0% for the move on the announcement, an expected absolute move of . Removing it, the 18-day expiry’s volatility is 32.0%: the whole term structure beyond the event is one diffusive volatility plus one jump (Figure 8.4).