
सभी किताबें

पेशेवर

ऐप्स परिचय Coach लॉग इन पढ़ना शुरू करें

Quantitative Finance · शब्दावली

Fama–MacBeth regression, clustered standard errors क्या है?

अन्य नाम: Fama--MacBeth regression · clustered standard errors

Definition 16.12 Quantitative Methods · अध्याय 16 — Linear Models under Stress

A Fama–MacBeth regression (Fama and MacBeth, 1973) runs one cross-sectional regression per period and reports the time-series mean of the slopes, with standard error their standard deviation over T\sqrt T. Clustered standard errors compute the sandwich variance with the scores summed within clusters (firms, or periods), allowing any correlation inside a cluster and none across clusters.
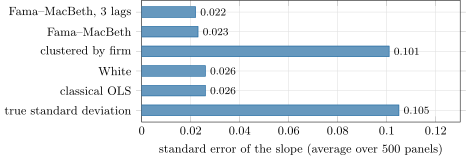
Standard errors of a panel slope when the characteristic and the residual both have a persistent firm component: only clustering by firm recovers the true sampling standard deviation (0.105); the classical, White and Fama–MacBeth standard errors understate it about fourfold. Data: the chapter’s tutorial, seeded.
Figure 16.5. Standard errors of a panel slope when the characteristic and the residual both have a persistent firm component: only clustering by firm recovers the true sampling standard deviation (0.105); the classical, White and Fama–MacBeth standard errors understate it about fourfold. Data: the chapter’s tutorial, seeded.
अध्याय में पढ़ें →