Todos los libros

Profesional

Apps Acerca de Coach Iniciar sesión Empezar a leer

Quantitative Finance · Glosario

¿Qué es First-passage time?

También llamado: hitting time

Definition 2.6 Quantitative Methods · Capítulo 2 — Brownian Motion

For a level bb, the first-passage time (or hitting time) of a continuous process XX is τb=inf⁡{t≥0:Xt=b}\tau_b = \inf\{t \ge 0 : X_t = b\}; it is a stopping time.

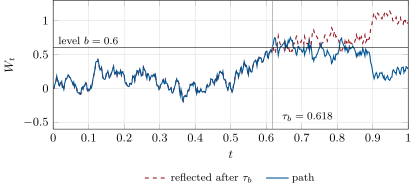
The reflection principle. After the first passage at b, the path (solid) and its mirror image in b (dashed) are equally likely continuations, so every path that ends below b after touching it is paired with one that ends above. Data: a seeded path of the tutorial.
Figure 2.2. The reflection principle. After the first passage at bb, the path (solid) and its mirror image in bb (dashed) are equally likely continuations, so every path that ends below bb after touching it is paired with one that ends above. Data: a seeded path of the tutorial.
Leer en el capítulo →