Semua buku

Profesional

Aplikasi Tentang Pelatih Masuk Mulai membaca

Quantitative Finance · Glosarium

Apa itu First-passage time?

Dikenal juga sebagai: hitting time

Definition 2.6 Quantitative Methods · Bab 2 — Brownian Motion

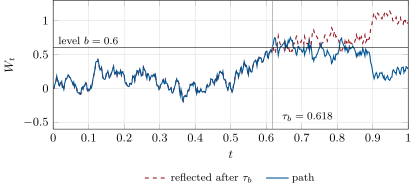
For a level bb, the first-passage time (or hitting time) of a continuous process XX is τb=inf⁡{t≥0:Xt=b}\tau_b = \inf\{t \ge 0 : X_t = b\}; it is a stopping time.

The reflection principle. After the first passage at b, the path (solid) and its mirror image in b (dashed) are equally likely continuations, so every path that ends below b after touching it is paired with one that ends above. Data: a seeded path of the tutorial.
Figure 2.2. The reflection principle. After the first passage at bb, the path (solid) and its mirror image in bb (dashed) are equally likely continuations, so every path that ends below bb after touching it is paired with one that ends above. Data: a seeded path of the tutorial.
Baca dalam konteks →