 المدرب
A forward-start option is an option whose strike is fixed at a future date as a proportion of the spot then, , and which expires at . It pays for a call.
أمثلة
Example 16.5 (Two forward smiles from one surface)
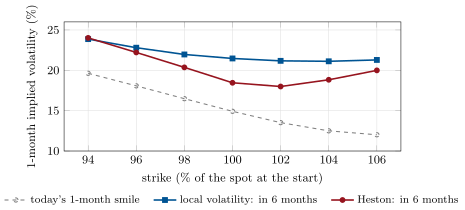
Chapter 9’s local volatility and chapter 10’s Heston model are both fitted to chapter 9’s surface: they reprice its one-year at-the-money call at 19.19% and 18.99% against the market’s 19.19%. Their one-month smiles starting in six months are very different (Figure 16.3). Local volatility gives 23.9% at 94%, 21.5% at the money and 21.3% at 106%, almost flat. Heston gives 24.0%, 18.5% and 20.0%, with a skew and a smile. Today’s one-month smile runs from 19.6% to 14.9% to 12.0%. Local volatility flattens the future smile, as chapter 9 found. Heston keeps its shape, and Bergomi observed that its forward smiles are more convex than today’s.