
सभी किताबें

पेशेवर

ऐप्स परिचय Coach लॉग इन पढ़ना शुरू करें

Quantitative Finance · शब्दावली

Full replication, sampled replication क्या है?

अन्य नाम: full replication · sampled replication

Definition 29.1 Strategies I: Equities and Futures · अध्याय 29 — The Asset Managers’ Strategies

Full replication holds every constituent of an index at its index weight. Sampled replication holds a subset of the constituents, with weights chosen so that the portfolio’s risk exposures match the index’s and its forecast tracking error is as small as possible, trading lower costs for some tracking error.
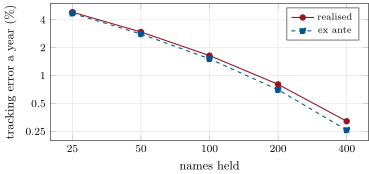
Sampled replication of the synthetic cap-weighted index: realised and ex-ante tracking error against the number of largest names held, with long-only weights minimising tracking error under the market’s true risk model, rebalanced every 63 days (log scales). Data: s1_assetmgr.replicate.
Figure 29.1. Sampled replication of the synthetic cap-weighted index: realised and ex-ante tracking error against the number of largest names held, with long-only weights minimising tracking error under the market’s true risk model, rebalanced every 63 days (log scales). Data: s1_assetmgr.replicate.
अध्याय में पढ़ें →