
Semua buku

Profesional

Aplikasi Tentang Pelatih Masuk Mulai membaca

Quantitative Finance · Glosarium

Apa itu Full replication, sampled replication?

Dikenal juga sebagai: full replication · sampled replication

Definition 29.1 Strategies I: Equities and Futures · Bab 29 — The Asset Managers’ Strategies

Full replication holds every constituent of an index at its index weight. Sampled replication holds a subset of the constituents, with weights chosen so that the portfolio’s risk exposures match the index’s and its forecast tracking error is as small as possible, trading lower costs for some tracking error.
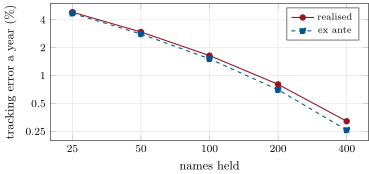
Sampled replication of the synthetic cap-weighted index: realised and ex-ante tracking error against the number of largest names held, with long-only weights minimising tracking error under the market’s true risk model, rebalanced every 63 days (log scales). Data: s1_assetmgr.replicate.
Figure 29.1. Sampled replication of the synthetic cap-weighted index: realised and ex-ante tracking error against the number of largest names held, with long-only weights minimising tracking error under the market’s true risk model, rebalanced every 63 days (log scales). Data: s1_assetmgr.replicate.
Baca dalam konteks →