 Coach
The futures-to-cash lead is the tendency of an index future’s price to move before the prices of the index’s constituents and of the funds that track it. A lead–lag estimator estimates the time shift at which two price series are most related: here the lag maximising the Hayashi–Yoshida cross-covariance of one series with the other’s clock shifted by , computed from all observations without synchronising them (Hoffmann, Rosenbaum and Yoshida, 2013).
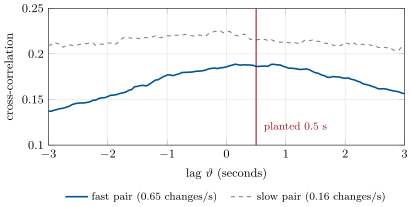
firm.tape, one hour, seed 10.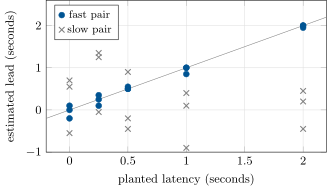
firm.tape, one hour per run.