 Coach
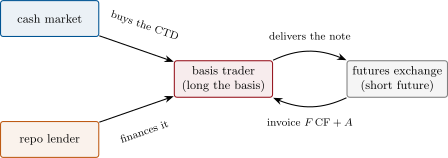
For a deliverable note with clean price , factor and future price : the gross basis is ; the net basis is the gross basis less the note’s carry to delivery (Proposition 5.3); the implied repo rate is the financing rate at which buying the note, financing it and delivering it into the future exactly breaks even,
with accrued interest today and at delivery, coupons received in between and days. A basis trade buys the note and sells the future in the ratio of the factor (long the basis), or the reverse (short the basis).
Examples
Example 6.8 (A December basket)
On 25 September 2026 a December ten-year future trades at 111-24+ (111.765625); delivery is assumed on 31 December, 97 days away, and repo is 3.90%. The table below shows five deliverable notes. The 3.875% of August 2033, the shortest, has the smallest net basis, two thirds of a 32nd, and the highest implied repo, 3.82%, eight basis points below repo: it is the CTD. The longest note would deliver at an implied repo of 0.05%. These notes and prices are illustrative.