
Tous les livres

Professionnel

Applis À propos Coach Connexion Commencer la lecture

Quantitative Finance · Glossaire

Qu'est-ce que « Gross basis, net basis, implied repo, basis trade » ?

Aussi appelé : gross basis · net basis · implied repo rate · basis trade

Definition 6.7 Markets II: Rates, FX and Credit · Chapitre 6 — Bond Futures

For a deliverable note with clean price PP, factor CF\mathrm{CF} and future price FF: the gross basis is P−F CFP - F\,\mathrm{CF}; the net basis is the gross basis less the note’s carry to delivery (Proposition 5.3); the implied repo rate is the financing rate at which buying the note, financing it and delivering it into the future exactly breaks even,

IRR  =  F CF+Adel+C−(P+A0)P+A0 360d,\text{IRR} \;=\; \frac{F\,\mathrm{CF} + A_{\text{del}} + C - (P + A_0)}{P + A_0}\,\frac{360}{d},

with accrued interest A0A_0 today and AdelA_{\text{del}} at delivery, coupons CC received in between and dd days. A basis trade buys the note and sells the future in the ratio of the factor (long the basis), or the reverse (short the basis).
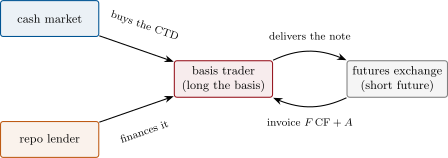
The cash-and-carry basis trade. The trader buys the cheapest note, finances it in repo, sells futures in the ratio of the factor, and delivers the note at expiry against the invoice price. It earns the implied repo rate and pays the repo rate; with leverage from repo, a few basis points on a large position is the business.
Figure 6.1. The cash-and-carry basis trade. The trader buys the cheapest note, finances it in repo, sells futures in the ratio of the factor, and delivers the note at expiry against the invoice price. It earns the implied repo rate and pays the repo rate; with leverage from repo, a few basis points on a large position is the business.

Exemples

Example 6.8 (A December basket)

On 25 September 2026 a December ten-year future trades at 111-24+ (111.765625); delivery is assumed on 31 December, 97 days away, and repo is 3.90%. The table below shows five deliverable notes. The 3.875% of August 2033, the shortest, has the smallest net basis, two thirds of a 32nd, and the highest implied repo, 3.82%, eight basis points below repo: it is the CTD. The longest note would deliver at an implied repo of 0.05%. These notes and prices are illustrative.

Lire dans le chapitre →