with ℓ=ln(F/K), z=αν(FK)21−βℓ and x(z)=ln((1−2ρz+z2+z−ρ)/(1−ρ)).
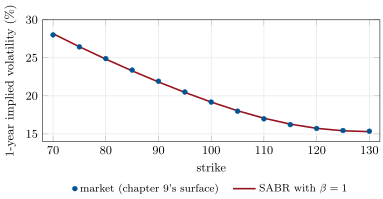
Figure 11.1. SABR with a lognormal backbone fitted to one equity expiry: 13 strikes, errors of at most 0.15 volatility point. Data: the tutorial.
Contoh
Example 11.3(A three-percent forward)
A one-year option on a forward rate of 3%, at-the-money Black volatility 20%, β=0.5, ρ=−0.6, ν=0.5: the cubic gives α=0.0346. The Black smile runs from 28.8% at a 2% strike to 15.8% at 4%; the same prices read as normal volatilities run from 70.8 to 55.0 basis points a year, 59.9 at the money. The normal smile is far less skewed: much of the Black skew is the lognormal model’s own scaling.
Example 11.4(SABR on an equity smile)
With β=1 (a lognormal backbone), SABR fitted to the one-year smile of chapter 9’s surface returns α=0.194, ρ=−0.68, ν=0.72, with a root-mean-square error of 0.07 volatility point and at most 0.15 point, at the 70 strike (Figure 11.1). One expiry, three free parameters, a good fit: SABR is a smile interpolator as much as a model.
 Pelatih