Coach
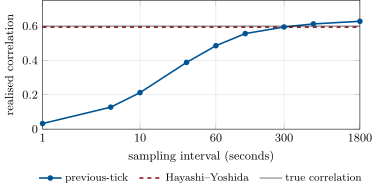
The Hayashi–Yoshida estimator (Hayashi and Yoshida, 2005) of the covariation sums the products of all pairs of returns, one from each asset, whose observation intervals overlap, with no interpolation. Refresh-time sampling samples both assets at the first time each has traded since the previous sampling time.