 Coach
Hierarchical risk parity (López de Prado) orders the assets by single-linkage clustering of correlation distances , and splits the capital recursively: each block of the ordered list is cut in two, and the halves receive capital in inverse proportion to the variance of their inverse-variance portfolios.
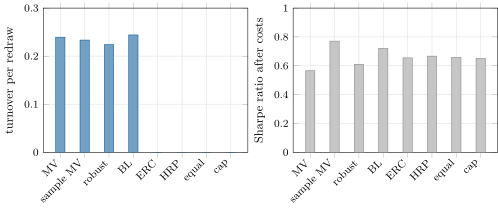
rs_allocation.