
Todos os livros

Profissional

Apps Sobre Coach Entrar Começar a ler

Quantitative Finance · Glossário

O que é Hierarchical risk parity?

Definition 26.5 Research Craft: Predictors, Backtests, Measurement, Portfolios · Capítulo 26 — Portfolio Construction II

Hierarchical risk parity (López de Prado) orders the assets by single-linkage clustering of correlation distances (1−ρij)/2\sqrt{(1-\rho_{ij})/2}, and splits the capital recursively: each block of the ordered list is cut in two, and the halves receive capital in inverse proportion to the variance of their inverse-variance portfolios.
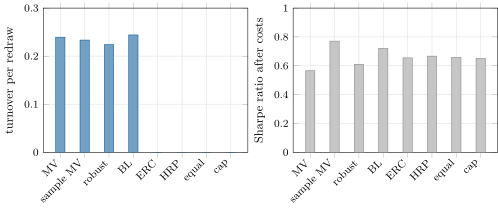
The eight long-only rules on fifty names: left, the one-way turnover when the forecast’s noise is drawn again; right, the Sharpe ratio after costs over 95 months (standard error about 0.4). Data: rs_allocation.
Figure 26.1. The eight long-only rules on fifty names: left, the one-way turnover when the forecast’s noise is drawn again; right, the Sharpe ratio after costs over 95 months (standard error about 0.4). Data: rs_allocation.
Ler no capítulo →