
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Historical scenario؟

Definition 22.2 Rates, Credit, XVA and Risk · الفصل 22 — Stress Testing and Scenarios

A historical scenario applies to today’s positions the moves the risk factors made over a past period: differences for rates and spreads, relative changes for prices.
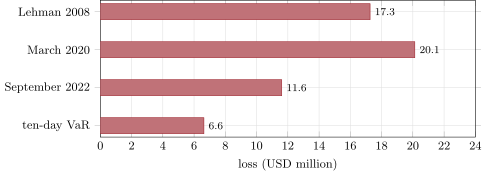
Losses of chapter 21’s book under three historical scenarios, against its ten-day 99% VaR. Each episode costs two to three times the VaR. Data: US Treasury par yields, ECB reference rates; the chapter’s tutorial.
Figure 22.1. Losses of chapter 21’s book under three historical scenarios, against its ten-day 99% VaR. Each episode costs two to three times the VaR. Data: US Treasury par yields, ECB reference rates; the chapter’s tutorial.

أمثلة

Example 22.3 (Three episodes on one book)

Chapter 21’s book (long ten-year Treasuries, short two-year, long euros, short yen, short a EURUSD straddle), revalued in full under three periods of Treasury and ECB data:

  • Lehman, 12 September to 10 October 2008: two-year yield −61-61 basis points, ten-year +15+15, EURUSD −3.52%-3.52\%, USDJPY −7.85%-7.85\%; a loss of USD 17.26 million;
  • March 2020, 6 to 20 March: −12-12 and +18+18 basis points, EURUSD −5.71%-5.71\%, USDJPY +5.11%+5.11\%; a loss of USD 20.13 million;
  • September 2022, 21 to 28 September: +5+5 and +21+21 basis points, EURUSD −3.50%-3.50\%, USDJPY +0.46%+0.46\%; a loss of USD 11.61 million.

The ten-day 99% historical VaR scaled from chapter 21 is USD 6.63 million: every episode loses two to three times as much (Figure 22.1). The short straddle, harmless on normal days, dominates the losses in all three.

اقرأ في الفصل →