Tous les livres

Professionnel

Applis À propos Coach Connexion Commencer la lecture

Quantitative Finance · Glossaire

Qu'est-ce que « Importance sampling » ?

Definition 26.6 Quantitative Methods · Chapitre 26 — Monte Carlo

Importance sampling draws XX from a density gg instead of ff and averages h(X)f(X)/g(X)h(X)f(X)/g(X), the payoff times the likelihood ratio (a Radon–Nikodym derivative); it is unbiased whenever g>0g > 0 where hf≠0hf \ne 0.

Importance sampling for a digital paying if S_T > 250 (S_0 = 100, = 25\%, one year; probability 1.21 × 10⁻⁴): relative standard error of 100 000 draws against the mean shift of the normal driver. Data: the chapter’s tutorial, seeded.
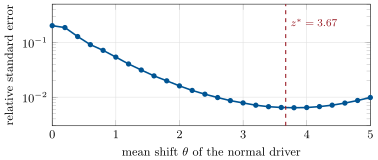
Figure 26.1. Importance sampling for a digital paying if ST>250S_T > 250 (S0=100S_0 = 100, σ=25%\sigma = 25\%, one year; probability 1.21×10−41.21 \times 10^{-4}): relative standard error of 100 000 draws against the mean shift of the normal driver. Data: the chapter’s tutorial, seeded.
Lire dans le chapitre →