 Pelatih
Kirk’s approximation prices a spread call by treating as lognormal with volatility and applying Margrabe’s formula:
Contoh
Example 16.5 (A calendar spread)
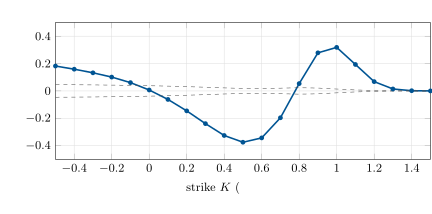
A call on the January forward (3.50) minus the July forward (2.74), strike 0.50, expiring at July delivery: the model gives volatilities of 34.8% and 58.1% to that date and a correlation of 0.970. Kirk’s approximation prices it at 29.41 cents per MMBtu against 29.78 by Monte Carlo (standard error 0.01), an error of 0.38 cent; at zero strike both give about 75.8 cents, Margrabe’s value. The error is largest near the money, where the approximation of the sum’s distribution matters most (Figure 16.2).