Todos os livros

Profissional

Apps Sobre Coach Entrar Começar a ler

Quantitative Finance · Glossário

O que é Kirk’s approximation?

Definition 16.4 Rates, Credit, XVA and Risk · Capítulo 16 — Commodity and Energy Derivatives

Kirk’s approximation prices a spread call by treating F2+KF_2+K as lognormal with volatility σ2F2/(F2+K)\sigma_2F_2/(F_2+K) and applying Margrabe’s formula:

C≈P(F1N(d1)−(F2+K)N(d2)),σK2=σ12−2ρσ1σ2b+σ22b2,b=F2F2+K.C \approx P\bigl(F_1N(d_1)-(F_2+K)N(d_2)\bigr),\quad \sigma_K^2 = \sigma_1^2-2\rho\sigma_1\sigma_2b+\sigma_2^2b^2,\quad b = \frac{F_2}{F_2+K}.
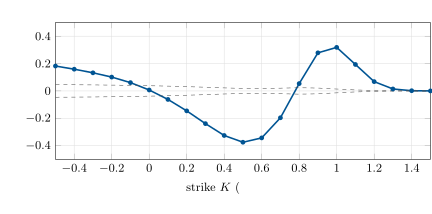
Error of Kirk’s approximation for the January–July calendar spread call against 400 000 Monte Carlo paths, by strike. The error is zero at zero strike (Margrabe is exact) and changes sign across the money; it stays under half a cent at every strike, on options worth from nothing to 1.26 dollars. Data: the chapter’s tutorial.
Figure 16.2. Error of Kirk’s approximation for the January–July calendar spread call against 400 000 Monte Carlo paths, by strike. The error is zero at zero strike (Margrabe is exact) and changes sign across the money; it stays under half a cent at every strike, on options worth from nothing to 1.26 dollars. Data: the chapter’s tutorial.

Exemplos

Example 16.5 (A calendar spread)

A call on the January forward (3.50) minus the July forward (2.74), strike 0.50, expiring at July delivery: the model gives volatilities of 34.8% and 58.1% to that date and a correlation of 0.970. Kirk’s approximation prices it at 29.41 cents per MMBtu against 29.78 by Monte Carlo (standard error 0.01), an error of 0.38 cent; at zero strike both give about 75.8 cents, Margrabe’s value. The error is largest near the money, where the approximation of the sum’s distribution matters most (Figure 16.2).

Ler no capítulo →