सभी किताबें

पेशेवर

ऐप्स परिचय Coach लॉग इन पढ़ना शुरू करें

Quantitative Finance · शब्दावली

Kolmogorov–Smirnov test क्या है?

अन्य नाम: Kolmogorov--Smirnov test

Definition 12.5 Quantitative Methods · अध्याय 12 — Testing and Multiple Testing

The Kolmogorov–Smirnov test of the null that X1,…,XnX_1, \dots, X_n are iid with a fully specified continuous cdf FF uses Dn=sup⁡x∣Fn(x)−F(x)∣D_n = \sup_x|F_n(x) - F(x)|, FnF_n the empirical cdf. Under the null, P(n Dn>λ)→2∑k≥1(−1)k−1e−2k2λ2\P(\sqrt n\,D_n > \lambda) \to 2\sum_{k \ge 1}(-1)^{k-1}e^{-2k^2\lambda^2}, whatever FF; the 5% critical value is λ=1.358\lambda = 1.358.

Power of the one-sided 5% test of a zero Sharpe ratio against years of independent daily returns, for true annual Sharpe ratios of 2, 1 and 0.5. The line at 80% power is crossed after 1.5, 6.2 and 24.7 years. Data: the chapter’s tutorial module.
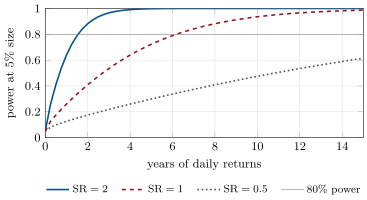
Figure 12.1. Power of the one-sided 5% test of a zero Sharpe ratio against years of independent daily returns, for true annual Sharpe ratios of 2, 1 and 0.5. The line at 80% power is crossed after 1.5, 6.2 and 24.7 years. Data: the chapter’s tutorial module.
अध्याय में पढ़ें →