
Semua buku

Profesional

Aplikasi Tentang Pelatih Masuk Mulai membaca

Quantitative Finance · Glosarium

Apa itu Low-risk anomaly, betting against beta?

Dikenal juga sebagai: low-risk anomaly · betting against beta

Definition 6.3 Strategies I: Equities and Futures · Bab 6 — Value, Quality and Low Risk

The low-risk anomaly is the observation that low-beta and low-volatility stocks have earned higher risk-adjusted returns than high-beta and high-volatility stocks: the security market line is flatter than the capital asset pricing model predicts. Betting against beta exploits it with a portfolio long low-beta stocks levered to a beta of one and short high-beta stocks delevered to a beta of one.
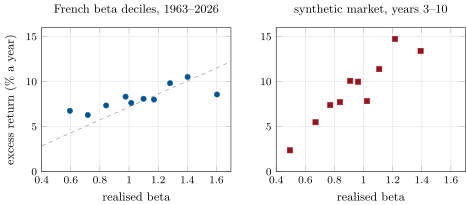
Realised beta and average return of beta-sorted deciles. Left: Kenneth French’s value-weighted portfolios formed on beta, excess returns over Treasury bills, with the line the capital asset pricing model implies at the market’s 7.2% (derived statistics; the raw series is not redistributed). Right: the synthetic market’s trailing-beta deciles, total returns. Data: s1_fetch_value.py, s1_factors.sml.
Figure 6.2. Realised beta and average return of beta-sorted deciles. Left: Kenneth French’s value-weighted portfolios formed on beta, excess returns over Treasury bills, with the line the capital asset pricing model implies at the market’s 7.2% (derived statistics; the raw series is not redistributed). Right: the synthetic market’s trailing-beta deciles, total returns. Data: s1_fetch_value.py, s1_factors.sml.
Baca dalam konteks →