 Coach
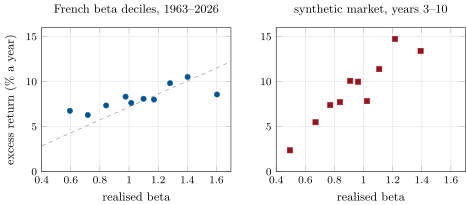
The low-risk anomaly is the observation that low-beta and low-volatility stocks have earned higher risk-adjusted returns than high-beta and high-volatility stocks: the security market line is flatter than the capital asset pricing model predicts. Betting against beta exploits it with a portfolio long low-beta stocks levered to a beta of one and short high-beta stocks delevered to a beta of one.
s1_fetch_value.py, s1_factors.sml.