 Coach
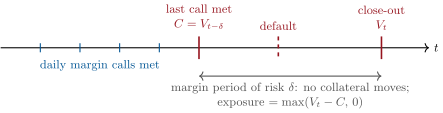
The margin period of risk is the time assumed between a member’s last payment of variation margin and the moment its portfolio has been hedged or liquidated by the clearing house: the horizon of the initial-margin calculation. It is a day or two for liquid listed futures and longer for cleared swaps and illiquid products.
Quantitative Finance · Glossary
What is Margin period of risk?
The exposure under a collateral agreement at is , where is the margin period of risk of One Quant Book 1: the collateral is the one agreed earlier. The exposure is the move of the netting set’s value over , plus the threshold and the minimum transfer amount.
Examples
Example 17.10 (Collateralising the netting set)
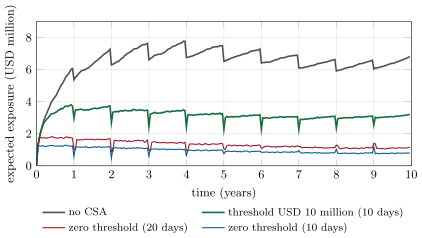
Under a two-way CSA with zero threshold and a minimum transfer amount of USD 500 000, the netting set’s EE falls to a nearly flat USD 1.30 million at its peak and its PFE to USD 6.45 million with a margin period of risk of ten business days; the EPE over the life falls from USD 6.44 million to 0.95 million, 15% of the uncollateralised figure. With twenty days the peak EE is USD 1.83 million, times higher; with a threshold of USD 10 million it is USD 3.81 million (Figure 17.4).